Restaurant Insurance | Sacramento & Northern California
Medical Practices • Dental Offices • Cyber Liability • Patient Data Protection
Restaurant Insurance for Sacramento & Northern California
Restaurant owners face unique risks, from kitchen fires and employee injuries to liquor liability, cyber incidents, equipment failures, and unexpected closures.
McClatchy Insurance Agency helps restaurant owners compare protection for property, customers, employees, operations, and the income needed to keep the business running.
A coordinated insurance review should reflect how your restaurant actually operates, not just the policies you already own.
Restaurant Businesses We Help Protect
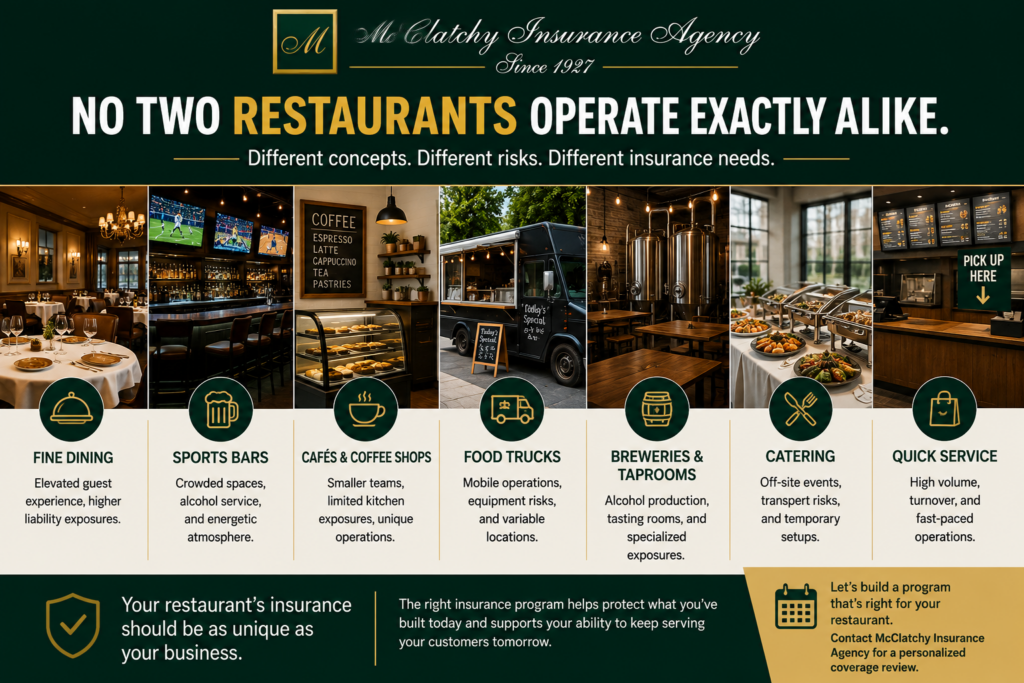
Breweries, Wineries & Taprooms
Alcohol service, events, and production-related operations may require specialized review.
Catering Companies
Off-site food preparation, transport, venues, and temporary events introduce changing exposures.
Coffee Shops & Cafés
Equipment, customer traffic, and employee safety remain important.
Family Restaurants
Dine-in service, kitchen operations, and staffing create multiple coverage needs.
Fine Dining Restaurants
Higher-value property, wine inventories, and specialized service can affect coverage.
Food Trucks & Mobile Vendors
Vehicle coverage, mobile equipment, location requirements, and event exposures should be reviewed.
Franchise Restaurants
Franchise contracts may impose specific insurance requirements and limits.
Multi-Location Restaurant Groups
Consistency of limits, property schedules, and business interruption protection matters across locations.
Quick-Service Restaurants
High transaction volume, drive-throughs, delivery, and staffing require careful evaluation.
Sports Bars & Taverns
Alcohol, events, entertainment, and late-night operations can increase liability exposures.
Restaurant Insurance Coverages Explained
Business Interruption
Coverage may replace qualifying lost income and continuing expenses after a covered property loss, subject to waiting periods and limits. A closure after a covered fire may stop sales while rent, payroll, and loan obligations continue. Review waiting periods, continuing expenses, restoration timelines, and any extra expense coverage; not every closure triggers payment.
Commercial Auto
Review business-owned vehicles and hired or non-owned auto exposures from deliveries and errands. A restaurant-owned delivery van presents different exposures from an employee using a personal car for catering. Confirm who owns and drives vehicles, what insurance applies, and whether hired or non-owned auto liability is needed.
Commercial General Liability
Helps address covered third-party bodily injury, property damage, and certain personal or advertising injury claims. Examples include customer slip-and-fall injuries and certain premises-related claims. Review limits, exclusions, contractual requirements, and whether product-related food claims are addressed by the policy.
Commercial Property
May cover buildings, kitchen fixtures, furnishings, inventory, and other insured property against covered causes of loss. A kitchen fire may damage cooking equipment, ventilation, dining furniture, inventory, and tenant improvements. Check replacement-cost values, deductibles, lease responsibilities, and exclusions before a loss.
Commercial Umbrella
May provide additional limits above certain underlying liability policies. A severe customer injury or vehicle-related claim can exceed underlying liability limits. Verify which policies are scheduled and whether liquor or auto exposures are included.
Crime
Review employee dishonesty, theft, and certain fraud exposures. Employee theft, fraudulent payments, and other dishonest acts may require different crime insuring agreements. Check employee dishonesty limits and social engineering exclusions rather than assuming every financial loss is covered.
Cyber Liability
Can address covered data breaches, ransomware, payment system attacks, and cyber business interruption. A payment-card compromise or ransomware incident can disrupt point-of-sale systems and online orders. Review incident response, notification expenses, business interruption, and exclusions for contractual payment-card assessments.
Employment Practices Liability (EPLI)
May address covered employment-related claims involving discrimination, harassment, or wrongful termination. Claims may involve discrimination, harassment, wrongful termination, or retaliation. Review defense provisions, wage-and-hour exclusions, deductibles, and procedures for documenting employee complaints.
Equipment Breakdown
Can help cover specified mechanical or electrical breakdown of insured equipment. Refrigeration, electrical panels, HVAC, and cooking systems may fail mechanically or electrically without a fire. Confirm covered equipment, repair costs, spoilage extensions, and whether resulting income interruption is included.
Food Spoilage
Review coverage for refrigerated or frozen food lost after a qualifying equipment or power failure. Refrigeration failures and qualifying power interruptions can destroy perishable inventory. Review covered causes, waiting periods, deductibles, valuation, and whether an off-premises utility failure is included.
Liquor Liability
For establishments serving alcohol, may address certain alcohol-related injury claims. Restaurants serving alcohol may face claims tied to injury or damage caused by intoxicated patrons. General liability does not necessarily replace liquor liability; review service practices, exclusions, and required limits.
Workers’ Compensation
California employers generally must maintain workers’ compensation coverage for employees. Kitchen burns, cuts, slips, and lifting injuries can lead to medical treatment and lost time. California employers generally must carry workers’ compensation for employees; accurate payroll classifications and safety training matter.
Building the Right Insurance Program for Your Restaurant
Restaurant insurance is not a single standard policy. A business owners policy may combine certain property and liability protections, but restaurants often need additional policies or endorsements.
Consider your premises, lease, kitchen equipment, liquor service, vehicles, payroll, cyber systems, food inventory, and revenue dependencies when selecting limits and coverage.
Coverage availability and exclusions vary. The goal is to identify gaps before an incident creates an expensive surprise.
The Biggest Risks Facing Restaurant Owners
Business Interruption
Extended closures can threaten cash flow even when physical damage is repairable. Even a repairable fire can force weeks of closure. Estimate how long inspections, permits, equipment replacement, and reopening could take, then compare that timeline with income coverage.
Customer Injuries
Slip-and-fall incidents, burns, and other customer injuries can result in claims. Wet floors, crowded entrances, uneven walkways, and hot beverages create claim exposure. Document cleaning routines, incident reports, and contractual responsibility for shared areas.
Cybersecurity & Technology
Online ordering, payment systems, reservations, and customer data create digital exposures. A compromised POS terminal or online-ordering account can interrupt sales and expose customer information. Assess payment processor obligations, incident response resources, and vendor dependencies.
Delivery & Takeout
Delivery drivers, hired vehicles, and changing service models may create additional liability. Staff using personal cars, third-party platforms, and off-site catering each create different liability questions. Review auto coverage and contracts rather than assuming the restaurant policy follows every delivery.
Employee Injuries
Kitchen burns, cuts, slips, lifting injuries, and repetitive work can cause workplace claims. Hot oil, sharp tools, repetitive movements, and slippery kitchen floors create workplace hazards. Review workers’ compensation, staff training, and return-to-work procedures.
Employment Practices
Staffing disputes and employment-related allegations may lead to defense costs. Scheduling disputes, harassment allegations, and terminations may lead to expensive defense costs. EPLI can address certain claims but often excludes or limits wage-and-hour disputes.
Equipment Breakdown & Food Spoilage
Refrigeration and kitchen equipment failures can disrupt operations and ruin stock. A failed walk-in cooler may destroy inventory and force menu reductions. Equipment breakdown and spoilage extensions have separate conditions; utility interruption may require additional coverage.
Kitchen Fires & Property Damage
Cooking equipment, grease, electrical systems, and water damage can lead to major losses. Grease buildup, cooking equipment, and ventilation systems can contribute to serious losses. Review fire suppression maintenance, property limits, tenant improvements, and rebuilding costs.
Liquor Liability
Alcohol service creates exposures not always covered by standard general liability. Service to an intoxicated guest can create substantial legal exposure. Training, incident documentation, and policy terms are important even when a restaurant has general liability insurance.
Reputation & Continuity
Customer trust, staffing, finances, and emergency response affect long-term survival. A closure, food safety incident, or cyberattack may damage customer confidence after physical repairs are complete. Plan communications and cash reserves; insurance does not automatically reimburse reputational loss.
Business Interruption: The Risk That Continues After the Fire
A realistic recovery estimate should include emergency cleanup, insurance adjustment, equipment replacement, inspections, health department requirements, staff scheduling, and reopening. Consider whether the policy’s restoration period and extra expense coverage match these delays.
A covered kitchen fire or other property loss may close a restaurant for weeks or months. Rent, loan payments, payroll, and other obligations can continue while revenue stops.
Business income and extra expense coverage may help with qualifying losses, subject to the policy’s triggers, waiting periods, limits, and restoration provisions.
The existing restaurant guide emphasizes that the prolonged financial disruption after an event can be more damaging than the initial physical loss.
Kitchen Fires, Property Damage & Equipment Failures
Fire suppression systems, hood cleaning, and refrigeration maintenance are operational controls, not substitutes for insurance. Verify whether spoilage from equipment failure or off-premises power loss requires an endorsement, and confirm the values of leased improvements.
Cooking equipment, grease buildup, refrigeration, electrical faults, and water losses can damage property and force closures.
Review commercial property limits, replacement cost terms, equipment breakdown protection, food spoilage coverage, and business interruption provisions together.
Maintenance, fire suppression systems, inspections, and documented emergency procedures remain important risk controls.
Liquor Liability, Customer Injuries & General Liability
A restaurant that serves alcohol should review liquor liability separately from general liability. Confirm the insured entities, service locations, limits, exclusions, and any requirements imposed by landlords or event venues.
Restaurants that serve alcohol should review liquor liability separately from general liability. Standard liability policies may not address every alcohol-related claim.
Customer slips, burns, and other injuries may trigger general liability claims, while liquor-related injuries can involve different coverage conditions.
Review contractual requirements, deductibles, limits, exclusions, and any umbrella or excess liability coverage.
Employees, Workers’ Compensation & Employment Practices
Restaurant employees face burns, cuts, slips, lifting injuries, and other occupational hazards. California employers generally must maintain workers’ compensation coverage.
Employment practices liability insurance may address specified employment-related allegations, while workers’ compensation addresses covered work-related injuries and illnesses.
Training, staffing procedures, safety documentation, and prompt incident reporting support a more resilient operation.
Cybersecurity, Payments, Online Ordering & Delivery
Online ordering, delivery apps, POS systems, and reservation platforms introduce vendor dependencies. Review how cyber coverage treats a payment-card incident, ransomware, fraudulent transfers, and interruption at a third-party provider.
Restaurants increasingly depend on payment terminals, online ordering, reservation software, delivery platforms, and customer information.
Cyber liability coverage may address certain data breaches, ransomware incidents, fraud, and qualifying network-related downtime. Delivery activities may require separate hired or non-owned auto coverage.
Review vendors, access controls, payment verification, cyber limits, and delivery arrangements as part of the overall insurance program.

Why Restaurants Really Go Out of Business
The original restaurant page explains that a restaurant may close because of cash-flow stress, prolonged interruption, rising expenses, staffing challenges, or an uninsured loss rather than the initial incident alone.
Insurance cannot eliminate ordinary business risks or poor profitability, but it can help manage specified financial consequences of covered events.
Review reserves, supplier dependencies, equipment maintenance, disaster response, and insurance limits before a crisis.
Restaurant Risk Management Checklist
Assess Business Income
Estimate revenue loss, ongoing expenses, and recovery time after a closure.
Check Contracts
Review landlord, lender, franchise, and vendor insurance requirements.
Document Equipment
Maintain inventories and replacement values for kitchen and refrigeration systems.
Evaluate Cyber Exposure
Review payment systems, online ordering, vendors, and customer information.
Inspect Safety Controls
Review fire suppression, slip prevention, food handling, and employee training.
Review Alcohol Service
Check liquor liability needs and responsible service procedures.
Illustrative Scenario: A Kitchen Fire Closes a Restaurant
A busy restaurant suffers a kitchen fire during dinner service. The fire damages cooking equipment, the ventilation hood, electrical systems, and surrounding kitchen areas. Smoke and water from firefighting efforts spread into the dining room, forcing the restaurant to close immediately.
Although the fire is extinguished quickly, the financial damage continues long after the flames are out. The owner must coordinate cleanup, replace damaged equipment, repair electrical and ventilation systems, and schedule inspections before reopening. Depending on the extent of the damage, the restaurant could remain closed for several weeks or even months.
Meanwhile, the bills don’t stop. Rent, loan payments, insurance premiums, and other ongoing expenses continue while the restaurant generates little or no revenue. Employees may lose hours, customers may establish new dining habits, and the owner faces the challenge of rebuilding the business while paying for repairs.
How the Right Restaurant Insurance Can Help
Business Interruption Insurance: May replace qualifying lost business income and certain continuing operating expenses during the covered restoration period, subject to policy conditions and limits.
Commercial Property Insurance: May cover eligible repairs or replacement of damaged cooking equipment, furnishings, fixtures, and other insured property resulting from the covered fire.
Equipment Breakdown Coverage: May provide additional protection for specified mechanical or electrical failures, although fire damage and equipment breakdown are subject to different coverage provisions.
Extra Expense Coverage: May help pay eligible additional costs to reduce the interruption, such as temporary equipment, alternative operating arrangements, or expedited repairs.
Could Your Restaurant Survive a 60- or 90-Day Closure?
The biggest financial threat may not be the fire itself. It may be the weeks or months of lost revenue that follow. Restaurant owners should review whether their property limits reflect current replacement costs, whether their business income coverage provides enough protection, and how long the policy allows for restoration.
The goal isn’t simply to repair the kitchen. It’s to protect the restaurant’s ability to reopen, retain employees, serve customers, and remain financially viable.
This scenario is illustrative. Actual coverage depends on policy terms, covered causes of loss, exclusions, deductibles, limits, waiting periods, and restoration provisions.
What Affects Restaurant Insurance Costs?
Pricing may reflect location, building characteristics, cooking operations, revenue, payroll, number of employees, claims history, liquor sales, property values, and coverage limits.
Delivery services, entertainment, outdoor seating, and multiple locations may create additional underwriting considerations.
Compare actual coverage terms, not just premiums. A low price may come with significant exclusions or insufficient limits.
Restaurant Insurance in Sacramento & Northern California
McClatchy Insurance Agency works with restaurant owners in Sacramento and throughout Northern California to review property, liability, workers’ compensation, business interruption, and other coverage needs.
Independent restaurants, cafés, bars, food trucks, caterers, franchises, and multi-location groups face different risks and contractual requirements.
A thoughtful annual review helps align insurance with changes in operations, revenue, staff, equipment, and locations.
Restaurant Insurance — Frequently Asked Questions
These answers are general information. Actual coverage depends on the policy terms, property, and insurer.
Are catering operations covered?
Can a food truck get restaurant insurance?
Can restaurants insure food delivery vehicles?
Do franchises have special insurance requirements?
Does restaurant insurance cover business interruption?
Does restaurant insurance cover cyberattacks?
Does restaurant insurance cover equipment breakdown?
Does restaurant insurance cover kitchen fires?
How much does restaurant insurance cost?
Is workers’ compensation required for restaurant employees in California?
What can help a restaurant reopen after a covered loss?
What insurance does a restaurant need in California?
What is food spoilage coverage?
What is liquor liability insurance?
What is the difference between general liability and liquor liability?
Why review restaurant insurance annually?
Protect Your Restaurant, Employees & Business Continuity
Review restaurant property, liability, workers’ compensation, liquor liability, food spoilage, and business interruption coverage with McClatchy Insurance Agency.
