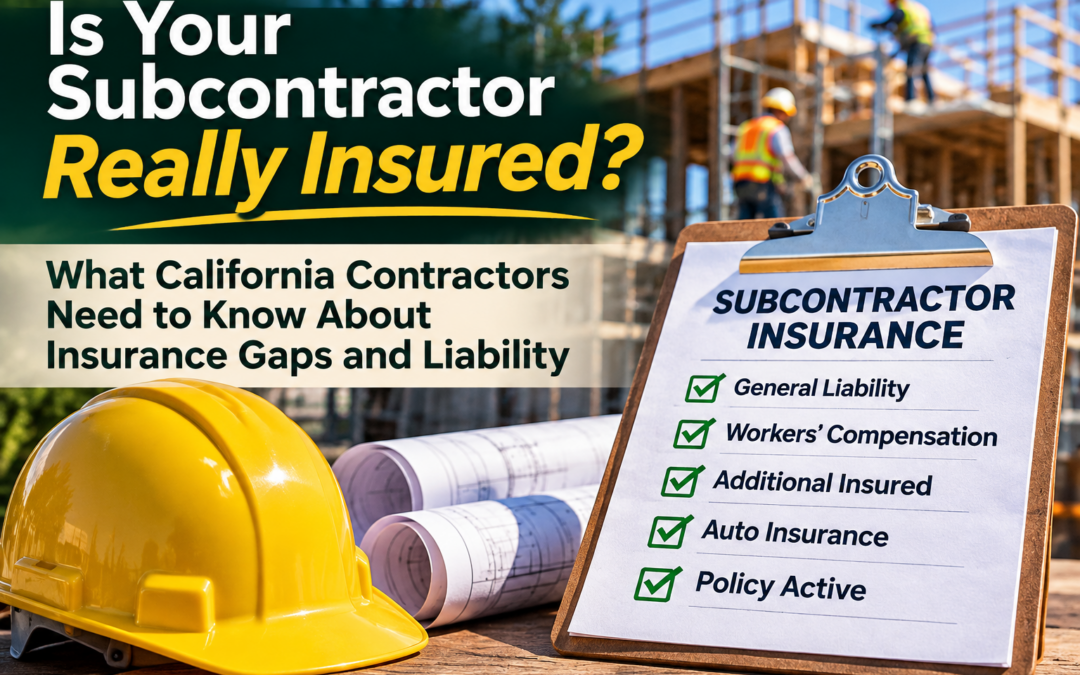
Is Your Subcontractor Really Insured? What California Contractors Need to Know About Insurance Gaps and Liability
A subcontractor hands you a certificate of insurance. You put it in the project file and assume your construction company is protected. But what happens if that subcontractor causes a serious accident, damages a client’s property, or allows their insurance to expire halfway through the job?
For California general contractors, commercial construction firms, roofing companies, HVAC contractors, electrical contractors, and plumbing businesses, subcontractor insurance is a critical part of managing construction risk.
A certificate of insurance alone does not guarantee coverage, make your company an additional insured, or eliminate your potential liability.
Understanding subcontractor insurance requirements can help protect your company from costly claims, uninsured losses, contract disputes, and unexpected workers’ compensation expenses. McClatchy Insurance helps California construction businesses evaluate these exposures as part of a comprehensive contractors insurance and bonds program.
What Happens If Your Subcontractor Doesn’t Have Insurance?
If an uninsured subcontractor causes an accident, the hiring contractor may face significant financial and legal exposure, depending on the circumstances.
Consider a commercial renovation project where a plumbing subcontractor accidentally damages a water line, flooding several occupied offices. The property owner expects the damage to be repaired. The general contractor contacts the subcontractor, only to discover that the subcontractor’s liability policy expired several weeks earlier.
Now the general contractor may face a property damage claim, contractual demands, legal expenses, and potential project delays. Whether the general contractor’s insurance responds depends on the allegations, policy language, contractual obligations, exclusions, and applicable California law.
Even when insurance provides a defense or pays an eligible claim, deductibles, self-insured retentions, and future insurance costs may affect the business. Your subcontractor’s insurance status can directly affect your company’s financial exposure.
Does a Certificate of Insurance Actually Protect Your Construction Company?
A certificate of insurance (COI) summarizes certain insurance information, such as the insurer, policy type, limits, and effective dates. It is useful evidence that coverage was reported when the certificate was issued.
However, a certificate generally does not:
- Amend the underlying insurance policy
- Automatically make your company an additional insured
- Guarantee coverage remains active throughout the project
- Override policy exclusions or limitations
- Prove that every subcontractor activity is covered
- Replace contractual insurance requirements
A certificate may show $1 million in general liability coverage while the underlying policy contains exclusions relevant to the work being performed. Before accepting a certificate, verify that the insurance meets the project’s actual requirements. McClatchy can assist with certificate of insurance requests and documentation reviews.
Certificate Holder vs. Additional Insured: What’s the Difference?
Certificate Holder
A certificate holder is identified on a certificate as receiving evidence of the named insured’s coverage. Being listed as a certificate holder does not, by itself, provide liability coverage under the subcontractor’s policy.
Additional Insured
An additional insured is a person or organization that qualifies for certain protection under another party’s insurance policy, generally through an endorsement or qualifying policy provision. A general contractor may require a plumbing subcontractor to provide additional insured coverage for specified liability arising from the plumbing subcontractor’s work.
Additional insured coverage may depend on endorsement wording, ongoing versus completed operations, the subcontractor’s acts or omissions, policy exclusions and limits, and contract requirements. A certificate naming your company as an additional insured is not a substitute for confirming the endorsement or policy language.
What Insurance Should California Subcontractors Carry?
Commercial Auto Insurance
Subcontractors using trucks, vans, or other business vehicles may need commercial auto liability. Employee-owned vehicles used for business may create hired or non-owned auto exposures.
Commercial General Liability Insurance
General liability may cover certain third-party bodily injury, property damage, and personal or advertising injury claims. Review limits, exclusions, additional insured requirements, and completed operations protection.
Contractors Equipment and Tools Insurance
Tools and mobile equipment may require inland marine or contractors equipment coverage. Do not assume a commercial auto policy covers tools stolen from a vehicle.
Professional Liability Insurance
Contractors providing design, consulting, or other professional services may need professional liability insurance for specified errors and omissions exposures.
Umbrella or Excess Liability Insurance
Large commercial projects may require limits above primary policies. Umbrella and excess policies can provide additional limits subject to their terms and underlying coverage requirements.
Workers’ Compensation Insurance
California employers generally must carry workers’ compensation for employees, and specified contractor license classifications must maintain coverage even without employees. Verify obligations rather than assuming a subcontractor qualifies for an exemption. Review workers’ compensation insurance for construction operations.
Can a General Contractor Be Responsible for an Uninsured Subcontractor’s Employee Injury?
Yes, in certain circumstances a California hiring contractor may face responsibility when a subcontractor’s employee is injured and the subcontractor lacks required workers’ compensation coverage. California law addresses contractor-subcontractor relationships, including some situations involving uninsured subcontractors. Outcomes depend on licensing, employment status, work performed, and applicable legal rules.
For example, a subcontractor’s employee suffers a serious fall while installing materials. If the subcontractor lacks required workers’ compensation, the hiring contractor may face statutory obligations or other legal exposure. Collect documentation before work begins and verify coverage remains active throughout the job.
Illustrative Scenario: An Uninsured Electrical Subcontractor Causes a Major Loss
A Sacramento commercial general contractor hires an electrical subcontractor for a renovated office building. The subcontractor provides a certificate at the start. Several weeks later, an electrical installation error allegedly causes a fire damaging finished walls, equipment, fixtures, and neighboring tenant spaces.
The owner demands compensation for damage and delays. The general contractor discovers the subcontractor’s liability policy was canceled before the incident.
The Financial Consequences
Contractual Liability: The owner may allege the general contractor failed to meet contractual responsibilities.
Defense Expenses: Legal representation may be needed to respond to claims.
Property Damage: Repairs to damaged areas and tenant property may be substantial.
Project Delays: Restoration may postpone completion and affect obligations.
Uninsured Exposure: Some losses may fall outside available coverage.
How the Right Insurance Program Can Help
A properly structured contractor insurance program may respond to certain covered third-party liability claims. Builders risk may address specified physical damage to property under construction, depending on insured interests, cause of loss, and policy terms. Neither automatically covers every construction defect or delay.
The best time to discover a subcontractor’s insurance problem is before work starts, not after a major claim.
This scenario is illustrative. Legal responsibility and insurance coverage depend on the facts, applicable law, endorsements, exclusions, and limits.
What Does Primary and Noncontributory Insurance Mean?
Construction contracts often require subcontractor insurance on a primary and noncontributory basis. These terms address how policies may respond when multiple insurers potentially cover a claim.
Primary generally means designated insurance responds first, subject to policy and endorsement terms. Noncontributory generally means the designated insurer agrees not to seek contribution from certain other insurance available to an additional insured, within applicable limits.
A contractual requirement does not automatically amend a policy. Verify the required endorsement or policy wording.
What Is a Waiver of Subrogation in Construction Insurance?
A waiver of subrogation generally restricts an insurer’s ability to pursue recovery from another party after paying a covered loss, to the extent provided by the applicable endorsement or agreement. Construction contracts may require waivers for workers’ compensation, general liability, or other policies.
A waiver of subrogation is not the same as additional insured coverage. Review each requirement separately.
How California Contractors Can Verify Subcontractor Insurance
Before allowing a subcontractor to begin work, establish a documented verification process.
Subcontractor Insurance Verification Checklist
- Additional Insured Status: Confirm endorsements or qualifying policy provisions.
- Commercial Auto Coverage: Verify coverage for vehicles used in the work.
- Contract Requirements: Compare insurance documents with the signed subcontract.
- Coverage Dates: Confirm effective and expiration dates and monitor renewals.
- General Liability Limits: Verify required limits.
- License Status: Check the California contractor license with CSLB.
- Operations and Exclusions: Review the actual trade and activities.
- Primary and Noncontributory Wording: Confirm required provisions.
- Umbrella or Excess Limits: Verify additional limits where required.
- Waiver of Subrogation: Review required waivers.
- Workers’ Compensation: Verify coverage or valid exemption eligibility.
On longer projects, a one-time certificate review may not be sufficient. Coverage can expire, be canceled, or change before work is finished.
What Happens If a Subcontractor’s Insurance Expires During a Project?
Insurance can expire or be canceled while construction is underway. An expired policy generally does not respond as though it remained active, although the outcome depends on the coverage type, triggering event, and policy terms.
Track expiration dates and request updated documentation before lapses. Do not rely solely on a certificate to guarantee cancellation notice.
Does Additional Insured Coverage Apply After Construction Is Completed?
Not necessarily. Additional insured protection for ongoing operations may differ from completed operations coverage. A general contractor could face a claim months after work ends—for example, water damage allegedly caused by a completed plumbing installation.
Whether coverage applies depends on the endorsement, policy, allegations, and other conditions. Review completed operations requirements before accepting subcontractor documents.
Frequently Asked Questions About Subcontractor Insurance in California
Can I be held liable if my subcontractor has no insurance?
Potentially. The outcome depends on contracts, California law, allegations, and circumstances. Uninsured subcontractors create exposure particularly for employee injuries and third-party property damage.
Does a certificate of insurance guarantee coverage?
No. It reports insurance information but does not guarantee that a policy is active or covers a particular claim. Verify coverage and endorsements.
Does general liability cover a subcontractor’s employee injuries?
General liability is not a substitute for workers’ compensation. The claim may involve workers’ compensation, employers liability, exclusions, and applicable law.
Does being a certificate holder make me an additional insured?
No. Additional insured protection must arise from the policy terms or endorsement.
How often should contractors verify subcontractor insurance?
Before work begins and when policies renew, expire, or materially change. Longer projects may require ongoing monitoring.
Is subcontractor insurance required by California law?
Requirements depend on coverage type, license classification, employment circumstances, and law. Some requirements arise from contracts rather than general statutory mandates.
What insurance should a general contractor require?
Common requirements include general liability, commercial auto, and workers’ compensation, with endorsements, waivers, or excess limits as appropriate to the trade and project.
What if my subcontractor hires another subcontractor?
Lower-tier subcontracting can create additional gaps. Review approval procedures, contracts, and verification for every relevant tier.
Protect Your Construction Company Before the Next Project Begins
Your company should not discover an insurance gap after an accident, lawsuit, or major property damage claim. Whether you manage commercial construction projects or run a roofing, HVAC, electrical, or plumbing business, subcontractor verification belongs in your risk management process.
McClatchy Insurance helps California contractors evaluate liability coverage, additional insured requirements, workers’ compensation exposures, and broader insurance needs.
Request a Contractors Insurance Quote or explore Contractors Insurance and Bonds.
Important California Insurance and Legal Disclaimer
California insurance laws, contractor licensing requirements, workers’ compensation obligations, and regulatory interpretations can change. This article is general educational information and does not constitute legal advice or guarantee insurance coverage. Verify current requirements directly with the California Contractors State License Board (CSLB) and California Department of Industrial Relations (DIR), and consult qualified legal or insurance professionals when appropriate. Coverage depends on policy language, endorsements, exclusions, limits, applicable law, and each claim’s circumstances.
